I have been watching one number for a year now and it barely moves.
ARC publishes the share of US agency transactions settled through NDC. It was 21.4% in May 2025. It was 21.6% in May 2026. Still 21.6% in June.
Twelve months, twenty basis points.
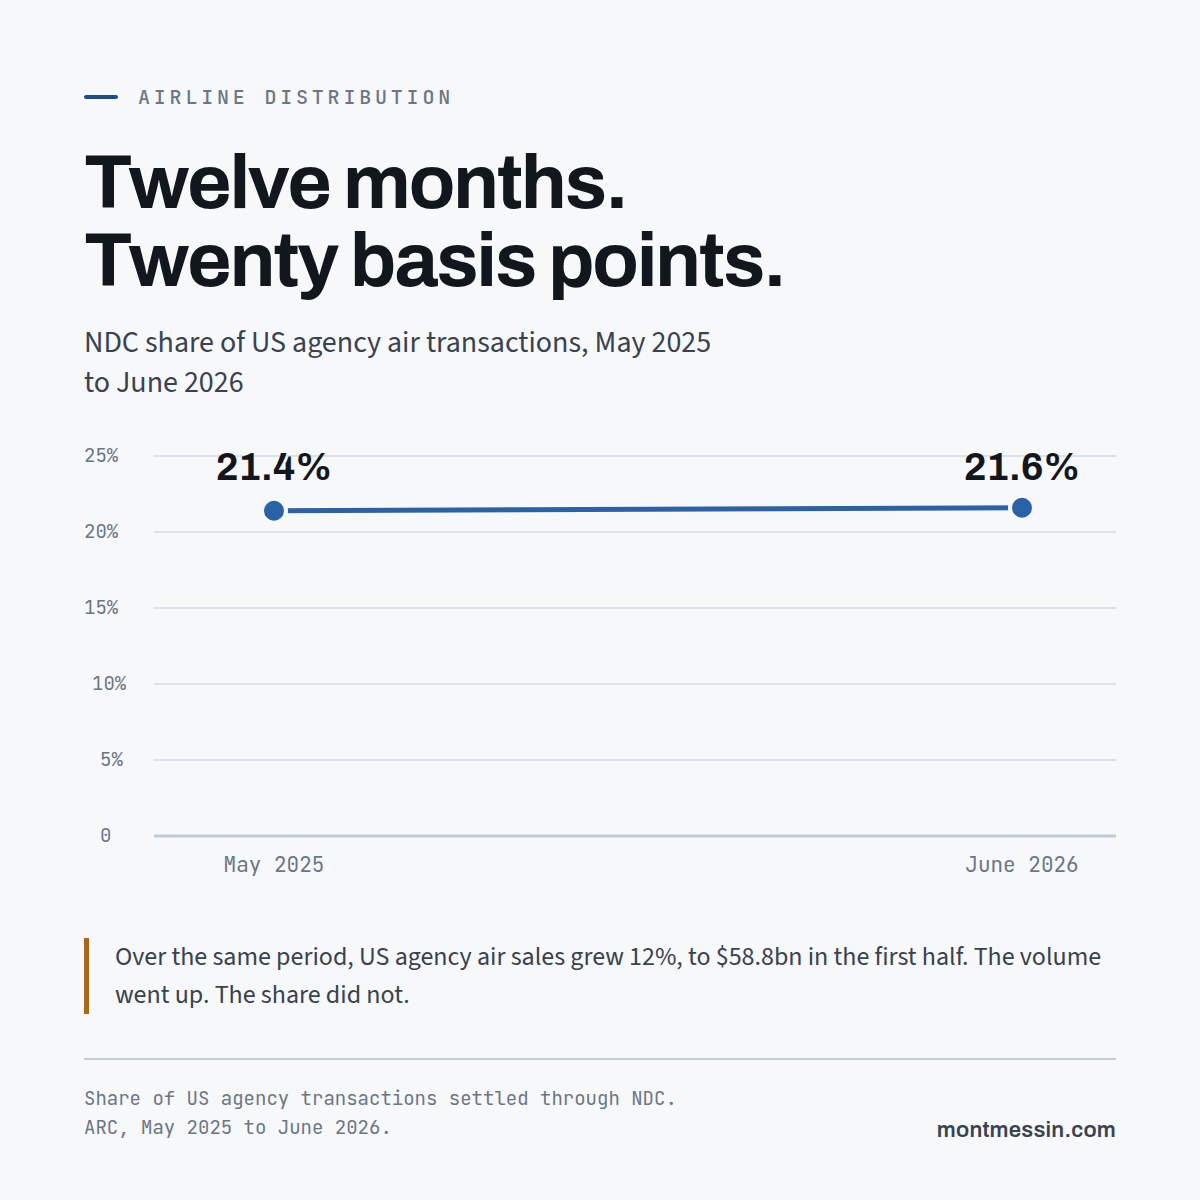
What makes it interesting to me is that the market itself grew. US agency air sales were up 12% in the first half, to $58.8bn. So NDC volume went up. The share did not.
You also see numbers like corporate NDC bookings up 168% year on year. I think both are true. They are measuring different things. One is a segment growing quickly from a small base, the other is the whole market.
I do not have a clean answer for why it flattened here. My own feeling is that it has less to do with standards and more to do with what happens after the booking, and I will come back to that in a few weeks. The NDC chapter of Airline Distribution Explained works through that servicing gap and what it costs.
Curious what others are seeing. A plateau, or just a pause?
What I left out
The number is US agency transactions only, from one reporting body. It says nothing about direct channels, about Europe or about Asia, and I framed it as if it described the whole picture.
Share is also not volume. US agency air sales grew 12% in the first half, so NDC volume went up while the share stood still. Both readings are true and they support different arguments.
Three months later I would lead on servicing rather than on the share, and use this number as the supporting evidence rather than the headline.
Sources
- NDC at 21.4% of ARC-settled transactions in May 2025 and 21.6% in May 2026: Travel Distribution News, 19 June 2026
- Still 21.6% in June 2026, 1,190 agencies reporting NDC activity: ARC via PRNewswire, 16 July 2026
- H1 2026 US agency air sales of $58.8bn, up 12%: same ARC release
- Corporate NDC bookings up 168% year on year, Q4 2025: Accelya
The ARC share figure is published monthly. It was current when this was written.